

If you made a commercial real estate investment five or so years ago, there’s a good chance that your financial outlook has changed since then, especially if you own an older building in Los Angeles with RSO units.
Rising expenses, changes to equity, and loan maturity, have completely changed the math of your investment. Suddenly you’re facing important decisions about what to do next.
The good news is that you have options.
Continue reading for helpful tips on how to manage a maturing loan on your rent-controlled Los Angeles apartment building.
A Note on the Los Angeles Market
Some important context for this resource: When it comes to multifamily real estate, Los Angeles is its own entity. While there’s been some pessimism in the national press about commercial investments at large, these headlines aren’t always relevant to LA.
Some important context for this resource: When it comes to multifamily real estate, Los Angeles is its own entity. While there’s been some pessimism in the national press about commercial investments at large, these headlines aren’t always relevant to LA.
What we’re seeing in the Los Angeles apartment market right now is a reset. Interest rates and cap rates have changed over the last few years. Now, property values are adjusting to match.
This creates a difficult scenario for building owners with maturing debt, but it’s also a knowable one. Nine times out of ten, the right decision comes down to math.
Five Year Outlook
Los Angeles’ multifamily real estate market was hit with a wave of liquidity from 2020 to 2022. During this time, many investors locked in ideal, low cost loans between 3% and 3.5%.
Fast forward five or six years and that debt is rolling over. Refinancing rates are close to (or at) 7%, creating significant pressure for many building owners with maturing loans. Add in other factors like inflation, rate control, and capital expenses, and things become even more challenging.
Build your commercial real estate knowledge with these related readings.
- How to Stay Up-to-Date with LA’s Housing Policies and Regulations
- How Does a 1031 Exchange Work in California?
- Who’s Who in Real Estate
The Challenge
Let’s look at an example scenario based on real clients we’ve worked with. While the details and numbers will be different from your building, the same challenges and principles apply.
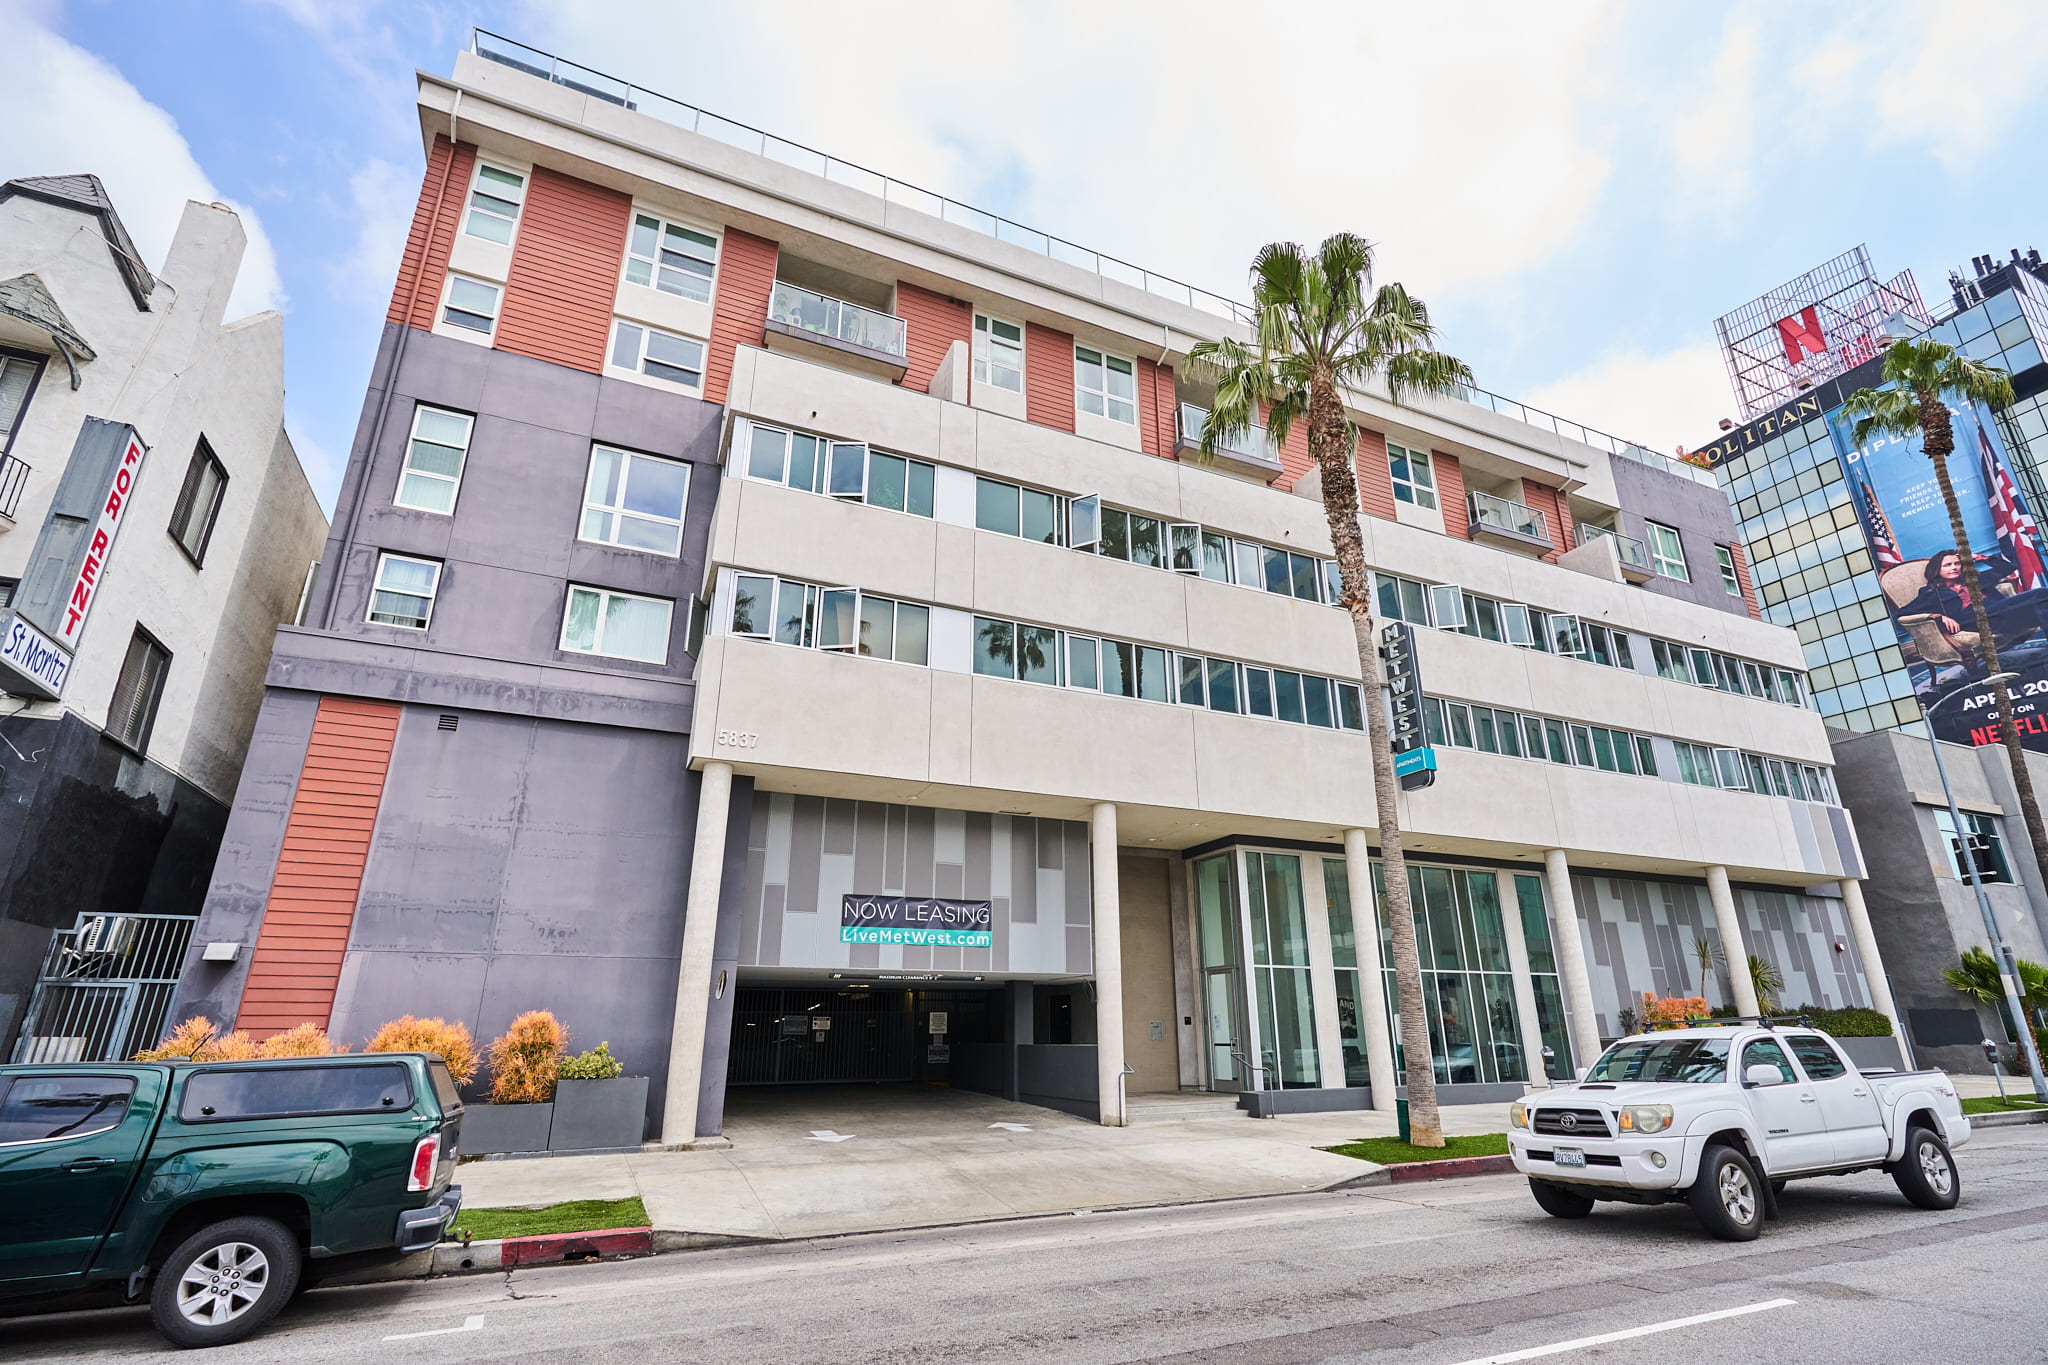
Our example is a rent-controlled (LA RSO) 16 unit apartment building that’s about 80 years old. It was purchased approximately five years ago, and the owner’s loan is set to mature in the next 12 months.
Here’s how the numbers have changed since 2020.
In 2020
- Value: $5,500,000
- NOI: $189,000
- Capitalization: 3.4%
In 2026
- Value: $4,250,000 (down 23%)
- NOI: $234,000 (up 24%)
- Capitalization: 5.5% (up 62%)
In addition to that, the owner of the building has made a number of capital investments in the last few years, including a new roof, windows, water heaters, and an intercom system. They also have four tenants (out of 16) who are paying significantly below-market rent.
Sound Like You?
If you made a commercial real estate investment five or so years ago, there’s a good chance that your financial outlook has changed since then, especially if you own an older building in Los Angeles with RSO units.
The good news is that you have options.
What Are Your Options?
If your loan is approaching maturity and you are worried about a significant jump in interest costs, you have five main options. We’ve outlined them below, ranging from “least painful” to “last resort”.
1 Break-Even Refinance
This option requires no upfront cash. Your refinancing (refi) covers the old balance and you get to keep the building. However, your cash flow and cash on cash return drop sharply.
2 Cash-In Refinance
You bring cash to the table to pay down a chunk of your balance. You’ll earn less every month under your refi terms.
3 Sell Your Building
You sell the building at current market value, paying off the loan and pocketing the remaining equity. This allows you to remove yourself from the problem and redeploy your money elsewhere.
While you may not get the type of return you hoped for 5 years ago, selling now can prevent you from digging a deeper financial hole.
4 Sell With Help From Your Lender
Depending on the circumstances (and whether a broker can pitch the solution successfully) your lender may assist in your building sale while providing you with partial loan forgiveness or an extension.
5 Hand Back the Keys
Lastly, if all other options are exhausted, you can hand off the property to your lender. This is an absolute last resort that should only be chosen if it’s the only option left. You may still be on the hook for recourse depending on the terms of your loan.
Recourse vs Non Recourse
As you decide to hold or sell, there are two types of debt liability that you should be aware of: recourse and non recourse.
If you have a recourse loan, you’ll be liable for the full amount no matter what. Let’s say your original loan is $5,000,000 and the lender only gets $4,000,000 from the sale. They can come for your other assets and belongings to recuperate their losses (LLCs, your primary residence, vacation home, etc.).
With a non recourse loan, the lender’s remedy is simply the property.
In the case of older, rent controlled buildings, most owners have non recourse loans. However, you should always double check the terms of your debt before making a decision.
Considering a multifamily property sale? Uncover more portfolio-optimizing advice with these related blog posts.
- Inheriting a Rental Property: What Are My Options?
- How Much Can I Sell My Apartment Building For?
- How The Neema Group’s 3-Phase Process Makes Multifamily Real Estate Easy
Repricing is a Symptom of the Market
Don’t let your emotions keep you attached to an investment that’s simply not working. Too many investors worry that selling is a form of giving up or admitting to a mistake. It’s not.
As an owner, some things are simply out of your control. Well-run buildings in Los Angeles get repriced by the market all the time. What matters most is how you adapt when external factors create new economic realities.
Look at the Numbers
When it comes to handling rising costs, it’s important to remove emotion from the decision. By focusing on where the math makes the most sense, you can move ahead with clarity and set yourself up for success in your next chapter.
Ask yourself, “would I buy this building today at its market value with this debt?”. If the answer is no, why keep it?
Look at the cash-on-cash. If you’re only going to earn 2% or 3% on your equity with no growth, why keep it?
Look at alternative options. By taking your remaining equity off the table, you unlock all kinds of new opportunities to redeploy it elsewhere. Make your money work for you.
Let’s Talk Taxes
Lastly, a few notes on taxes.
Selling your building will come with a smaller tax hit if you have a high tax basis. This could make your decision a little easier. You can also request a property tax reassessment if you decide to sell.
If your building declines in value on paper, that’s not the same as a deductible loss in the eyes of the IRS. A loss only applies if you sell for less than you paid.
If you have tax questions, talk to your CPA.
Get Confidential Support
This article is designed to be a high level, introductory resource. If you have concerns or questions about your multifamily property, there’s no substitute for professional advice.
Get in touch with The Neema Group today for a discreet, no obligation hold vs sell analysis.
Need multifamily real estate support? Call (213) 797-2290 or email us at neema@marcusmillichap.com to reach our team of experts.
Empower Your Investment
Whether expanding or transitioning your real estate asset or portfolio, we have the proven strategies and market wisdom to help you succeed.